

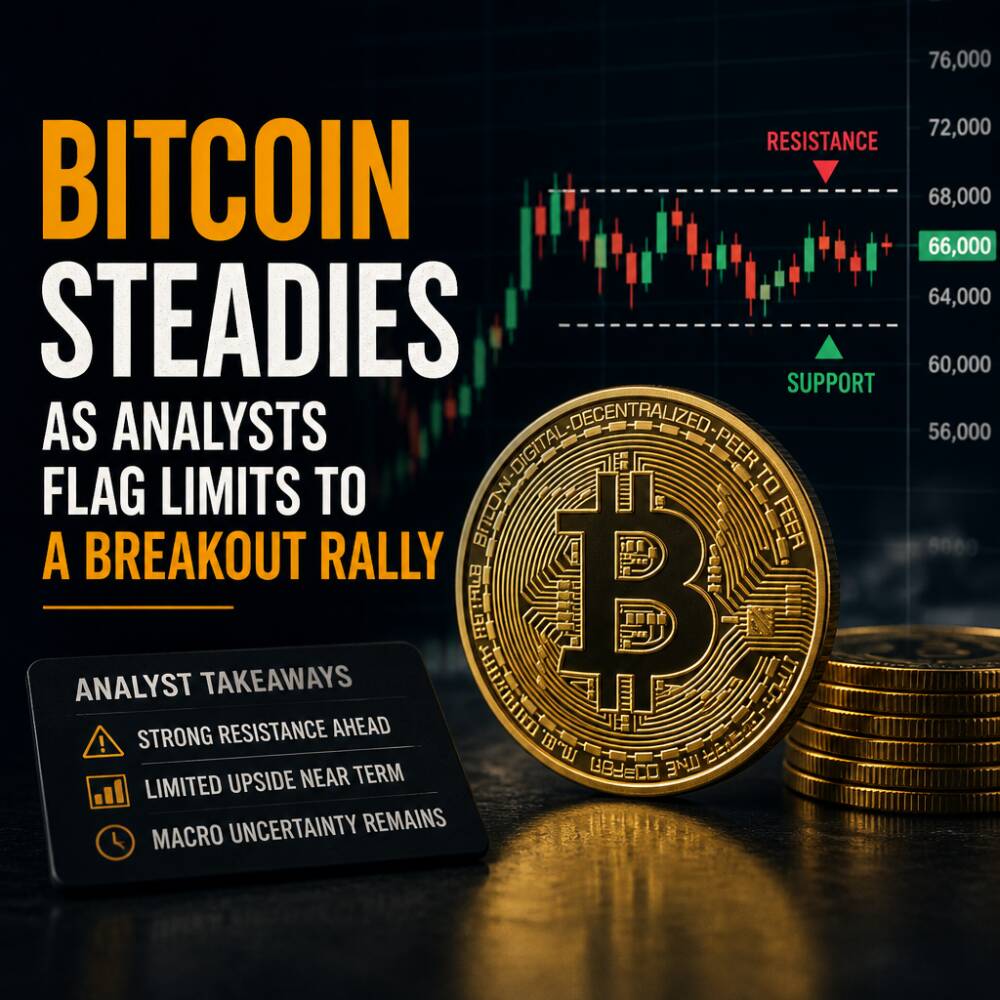
Bitcoin struggled to establish a decisive upside breakout in October, holding near the low-$80,000s after multiple tests of support and a rebound earlier in the quarter. The largest digital asset was trading around $83,400 on October 14, following a brief dip toward $81,000 earlier in the week, while resistance in the mid-$80,000s capped attempts to push higher.
The lack of follow-through comes as macro conditions remain a headwind for risk assets, with investors focusing on elevated Treasury yields and oil-driven inflation risks ahead of an inflation report. At the same time, market participants say spot Bitcoin exchange-traded fund (ETF) demand—once a key tailwind in late September—has weakened into more uneven flows during October.
Key takeaways
- Price move: Bitcoin hovered near the low-$80,000s, after testing support around $81,000; it has repeatedly failed to break through resistance in the mid-$80,000s.
- Catalyst: Rising or still-elevated US bond yields and energy-linked inflation pressures appear to be limiting risk appetite and competing for investor capital.
- Demand signal: Spot Bitcoin ETF flows turned inconsistent in October, even though at least one session on October 13 returned net inflows.
- Implication: Investors are watching for renewed ETF inflow momentum and trading activity to confirm whether consolidation near support can evolve into a sustained uptrend.
What drove the move
Market commentary pointed to macroeconomic pressure as a central factor behind Bitcoin’s stalled breakout attempts. According to Yves Renno, head of trading at Wirex, the inability to surpass $86,000 was driven by a combination of energy-driven inflation risk and rising government bond yields.
Renno said Brent crude trading above $106 a barrel and the 10-year US Treasury yield reaching a pace of increase not seen since 2022 have weighed on expectations for returns. The framework, he argued, is straightforward: higher yields can compete with cryptocurrencies for investor capital, making it harder for Bitcoin to sustain upside momentum.
In parallel, analysts cited waning urgency in crypto trading activity and a shift in ETF-led buying behavior as factors that could determine whether Bitcoin finally clears its current range. Spot Bitcoin ETF flows strengthened late in September, but in October they have become more uneven.
Market reaction and what it implies
Equities were steady but volatile at the index level as investors balanced corporate earnings with interest-rate expectations. The S&P 500 ended October 13 at 7,805.45, just below the prior week’s record high, while the Dow Jones Industrial Average slipped 0.35% and the Nasdaq Composite fell 0.15%. Even with modest index moves, individual stock swings suggested investors were actively repricing rate sensitivity.
In crypto, the price pattern has looked constructive on the surface—Bitcoin has held support—but participants say the recovery has not been accompanied by the kind of broad-based demand that typically supports breakouts.
According to Martin Gaspar of FalconX, average daily spot and futures trading volumes during the first five days of October were running 12% and 19% below their respective September averages. That divergence—stronger price stability paired with weaker activity—raised questions about how much conviction sits behind the rebound.
Gaspar said Bitcoin tested $81,000 twice within a week but struggled to break higher decisively, describing the behavior as consolidation with limited conviction rather than outright weakness.
Other industry views reinforced that interpretation. Bernardo Brites, CEO of Trace Finance, said there are buyers “underneath” the market but that they are not paying up. He argued earlier declines likely eliminated many forced sellers, helping Bitcoin remain in the low-$80,000s even during periods of ETF outflows. However, Brites said a sustained move higher still requires fresh demand, particularly as ETF buying momentum appears to be slowing.
Limited growth in stablecoin supply was also cited as a potential constraint on the amount of incremental buying power entering the market. Without stronger ETF inflows or another source of capital, Brites suggested Bitcoin could continue to consolidate rather than establish a new upward trend.
ETF flows and the “Uptober” debate
Spot Bitcoin ETF flows provided a clearer read on whether institutional demand remained durable after late-September strength. Data show that US spot Bitcoin ETFs recorded approximately $3.08 billion in cumulative net inflows across nine consecutive trading sessions from September 17 through September 29. That run included near-$1 billion inflows on September 21 and $714.7 million on September 22, according to the figures cited in the underlying flow table.
The streak ended on September 30 with net outflows of $148.7 million. October began with inflows of $102.7 million on October 1 and $189.9 million on October 2, but the pattern reversed on October 7 and October 8 with net outflows of $484.9 million and $244.1 million, respectively. After a smaller outflow on October 12, the funds recorded net inflows of $175.7 million on October 13. Even with that rebound, cumulative net flows for October remained negative at roughly $276 million through October 13.
Brites characterized the shift as more of a pause than an institutional exit, noting that despite nearly $730 million leaving US spot Bitcoin ETFs over two sessions earlier in October, Bitcoin still held in the low-$80,000s. Chris Kline, chief operating officer and co-founder of BitcoinIRA, cautioned against overreacting to single-day ETF swings, arguing institutional allocations adjust to liquidity and market conditions rather than following a fixed daily cadence.
Investors are also weighing whether the traditional seasonal tailwind often nicknamed “Uptober” can override the current mix of macro pressure and inconsistent ETF demand. CoinGlass data cited in the report indicate that Bitcoin rose in 10 of the 13 Octobers from 2013 through 2025, with an average return of 18.52% and a median return of 12.73% across all 13 Octobers. Still, analysts noted the limited sample and that seasonal performance does not guarantee a rally—October has seen weak periods as well.
Gaspar argued early October trading has slowed, oil prices are elevated, and few immediate catalysts are evident, creating headwinds for the month. Zielke similarly said the weak start has fallen short of typical Uptober expectations, though time remains for that pattern to evolve.
Brites, however, said Bitcoin’s market structure has changed: he argued Bitcoin now trades more with ETF flows, interest rates, and the US dollar—factors that do not follow the calendar. He pointed to the Federal Reserve meeting on October 27–28 as a potential catalyst for the remainder of the month, given its influence on rate expectations.
Looking ahead, traders are likely to focus on whether spot Bitcoin ETFs return to more consistent net inflows and whether trading volumes pick up alongside price action. With a US inflation report on the calendar and the Federal Reserve’s October 27–28 meeting approaching, rate expectations could be a key driver of whether Bitcoin remains boxed in near support or gains the momentum needed for a sustained breakout.


